Inflation Ran Hot. The 10-Year Jumped. A Fed Governor Said Half a Point.
October prices came in above forecast, bonds sold off, and one Fed governor put a 50 basis point hike on the table for December. Here is what happened and what I am watching.
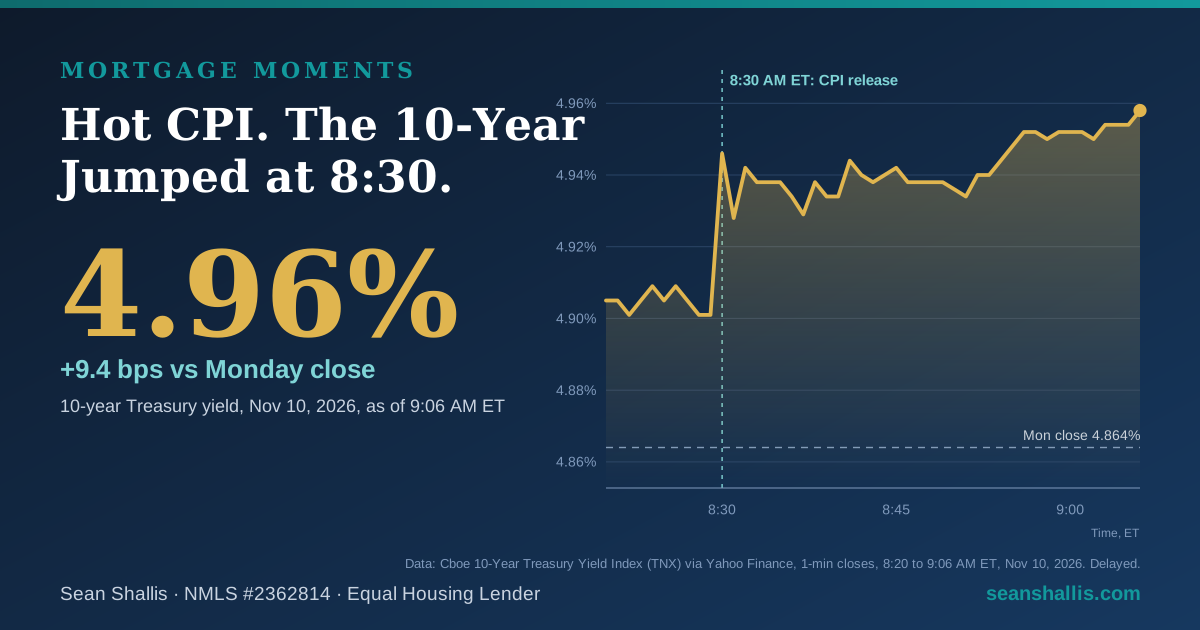
The 10-year yield, minute by minute, Tuesday morning. Data: Cboe 10-Year Treasury Yield Index (TNX) via Yahoo Finance, delayed. The jump lines up with the 8:30 AM ET CPI release.
The Facts, Short
Prices rose faster than expected
The consumer price index rose 0.4% in October. Economists polled by Dow Jones expected 0.3%. September was 0.6%. Core CPI, which leaves out food and energy, rose 0.3% against 0.2% expected, the same as September. The BLS did not publish a yearly rate this time because the 2025 shutdown left no October 2025 figure to compare against.
Bonds moved, the short end most
The 10-year Treasury yield jumped the minute the CPI data hit at 8:30 AM ET. By 9:06 AM ET it was near 4.96%, up 9.6 basis points from Monday's close of 4.862% (Tradeweb, via CNBC). In CNBC's first read of the morning, the 10-year was up more than 7 basis points at 4.938% while the 2-year, which tracks Fed expectations more closely, was up more than 15 basis points at 4.698%. The 30-year was near 5.29%. CNBC calls the 10-year the benchmark for mortgages.
Waller named the number
In a London speech hours before the data, Fed Governor Christopher Waller said he leans toward a 25 basis point hike in December. If core CPI came in "around 0.3 percent or even higher," he said, "I believe a 50 basis point hike in the policy rate should be considered at the December meeting. Hiking only 25 basis points would put our credibility at risk, a risk I am not eager to take." Core came in at 0.3%.
The calendar is short. Wholesale inflation numbers land Friday, and the Fed meets December 8 and 9. CNBC reported that markets had already largely priced in a 25 basis point hike, per CME FedWatch. Last week's jobs report showed 165,000 jobs added in October, more than double forecasts.
My Opinion, Labeled as One
Strong jobs, prices still running hot, and a Fed governor talking about a bigger hike. To me that makes “higher for longer” the case to plan around, not the worst case. That is my read, not a forecast. Bond yields can turn fast in either direction, and nobody knows the next move, including me.
Why the Fed Headline Hits a Mortgage
The Fed sets a short-term rate. Mortgages tend to price off longer bonds like the 10-year, plus a spread. In CNBC's first read today, the 2-year moved about twice as much as the 10-year. That is the bond market repricing the Fed's next few moves. The 10-year moving too is what reaches mortgage pricing, usually with a lag.
Being ready does not need a forecast. A pre-approval and a complete file let you act when pricing moves, instead of starting paperwork the same week everyone else does.
If You Are a Physician, Building, or Served
A new contract, a future start date and student debt make a physician file take longer to set up than a W-2 file. Start it before you need it. See physician loans. Building instead of buying? On a construction-to-permanent loan, when and how the permanent rate gets set matters more in a market moving this fast. Served? VA loans belong in the comparison.
If You Advise Clients
Higher rates for longer change the planning questions your clients bring you: pay cash or finance, how much to put down, whether to sell positions to fund a purchase. In my opinion the mortgage should fit the plan you built, not pull against it. The advisors I talk with want two things from a mortgage partner: someone their client can trust, and someone who stays in the mortgage lane and leaves the portfolio to them. If that is the partner you want for your clients, book a call with me.
What today means for your rate, your payment and your timeline is the part I will not guess at in a blog post. That takes your facts.
Your Situation, Not the Headline
Are you overpaying on your mortgage? Not sure?
Just ask Rosie. Find out instantly at seanshallis.com. Or book 15 minutes with me and bring your questions.
Learn more: Buy the Gap · Treasury Over 5% · Lock Before the Fed
These are my own personal opinions as an individual market observer. They are not the views of any employer, lender, bank or institution, none of which has reviewed or approved this post. Nothing here is financial, investment, tax or legal advice.
Sources (public reporting): CNBC, “10-year Treasury yield jumps after hot CPI, Waller half-point hike comment,” Nov 10, 2026; CNBC, October 2026 CPI report coverage, Nov 10, 2026; Federal Reserve Board, Governor Waller speech text, Nov 10, 2026; CoinDesk, Nov 10, 2026; CME FedWatch as reported by CNBC; Tradeweb 10-year quote via the CNBC app, 9:06 AM ET, Nov 10, 2026; chart data from the Cboe 10-Year Treasury Yield Index (TNX) via Yahoo Finance, 1-minute, delayed. Different data providers quote slightly different yields at the same moment. Yields are intraday third-party figures as of Tuesday morning, Nov 10, 2026, and change continuously. Futures pricing is other parties' expectations, not fact, and may be wrong. “Higher for longer” is my opinion, not a prediction.
Nothing here is a rate quote, an offer of credit, a commitment to lend or a guarantee of any rate, price, savings or outcome. All loans subject to credit approval and program guidelines; not all programs available in all states or for all loan amounts.
Sean Shallis · NMLS #2362814 · Equal Housing Lender
Keep reading
- Buy the Gap: Why I Would Look Before New Year'sOctober 23, 2026 · 3 min readRead it
- Treasury Over 5%. What's Going On, and How Does It Affect Me?October 2, 2026 · 4 min readRead it
- The Fed Decides Tomorrow at 2:00. Why Locking Today Isn't a Prediction. It's a Free Option.July 28, 2026 · 5 min readRead it